One loan, one closing
Purchase and renovation financed together, instead of a mortgage plus a separate renovation loan.
Whatever you pick stays on this browser and follows you from page to page. It is not sent to us.
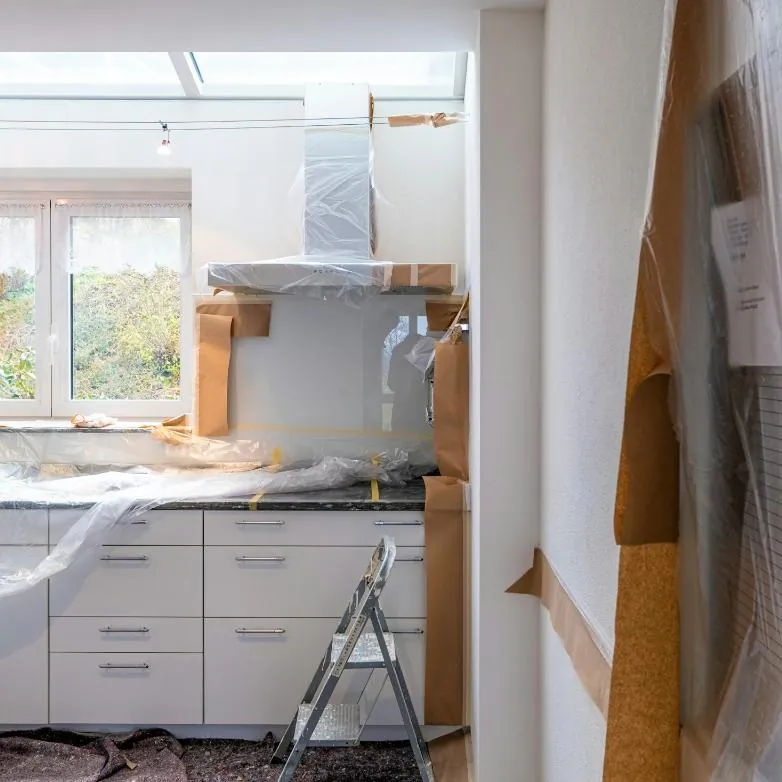
The FHA 203(k) program rolls the purchase of a home and the cost of repairing it into a single mortgage. It opens up the houses other buyers walk away from, and it can be used to refinance a home you already own that needs work.
Purchase and renovation financed together, instead of a mortgage plus a separate renovation loan.
The loan can be sized against what the home will be worth once the work is done.
A limited 203(k) for smaller, non-structural work and a standard 203(k) for larger projects.
Repair funds are held and paid out as the work is completed, not handed over up front.
You will need a licensed contractor's bid for the work before the loan can be sized.
The appraisal values the home as it will be after the repairs.
Repair funds go into an escrow account at closing.
The contractor is paid in draws as each stage is completed and inspected.
One FHA-insured loan that covers the price of the home and the cost of the repairs, so a house that needs work stops being a house you cannot finance.
Whether it is the right program depends on your credit, your savings and the property. We run it against the alternatives with your real numbers, and if another program suits you better, we say so.
Three details and we call you back, Monday to Friday.
Ready now? Apply online or call (954) 709-4659
The limited version covers smaller, non-structural repairs such as flooring, a kitchen or a roof. The standard version covers larger and structural work, and uses a HUD consultant.
Generally no. 203(k) repairs are done by a licensed contractor. We can tell you where exceptions exist.
Yes. A 203(k) can be used as a refinance to renovate the home you live in.
HUD sets completion timelines for each version of the program. We give you the current rules before you sign a contract.
Most permanent improvements: kitchens, bathrooms, roofs, flooring, systems, accessibility and energy upgrades. Luxury items such as a new pool are generally excluded.
Usually a little longer than a standard FHA purchase, because the contractor bid and the scope are part of the file. Getting the bid early is the biggest time-saver.
Start the secure application online, or call the office and talk it through first. Either way you get a real answer, not a range.